
The elevator is sold once. Then it gets serviced for 30 years.
by Alien Investor
#Stocks #ValueInvesting #Investing #Switzerland #Dividends #Nostr
────────────────
"Schindler does not sell cabins. Schindler sells a subscription to gravity."
────────────────
Schindler moves over two billion people every day. Almost nobody thinks about the company while riding. That is the whole point: invisible infrastructure that must be serviced by law, runs for 20 to 30 years, and then gets modernized.
The Swiss group just finished its four-year recovery plan with a record margin. The business is excellent. The question is what you pay for it.
────────────────
The moat: a loop, not a product
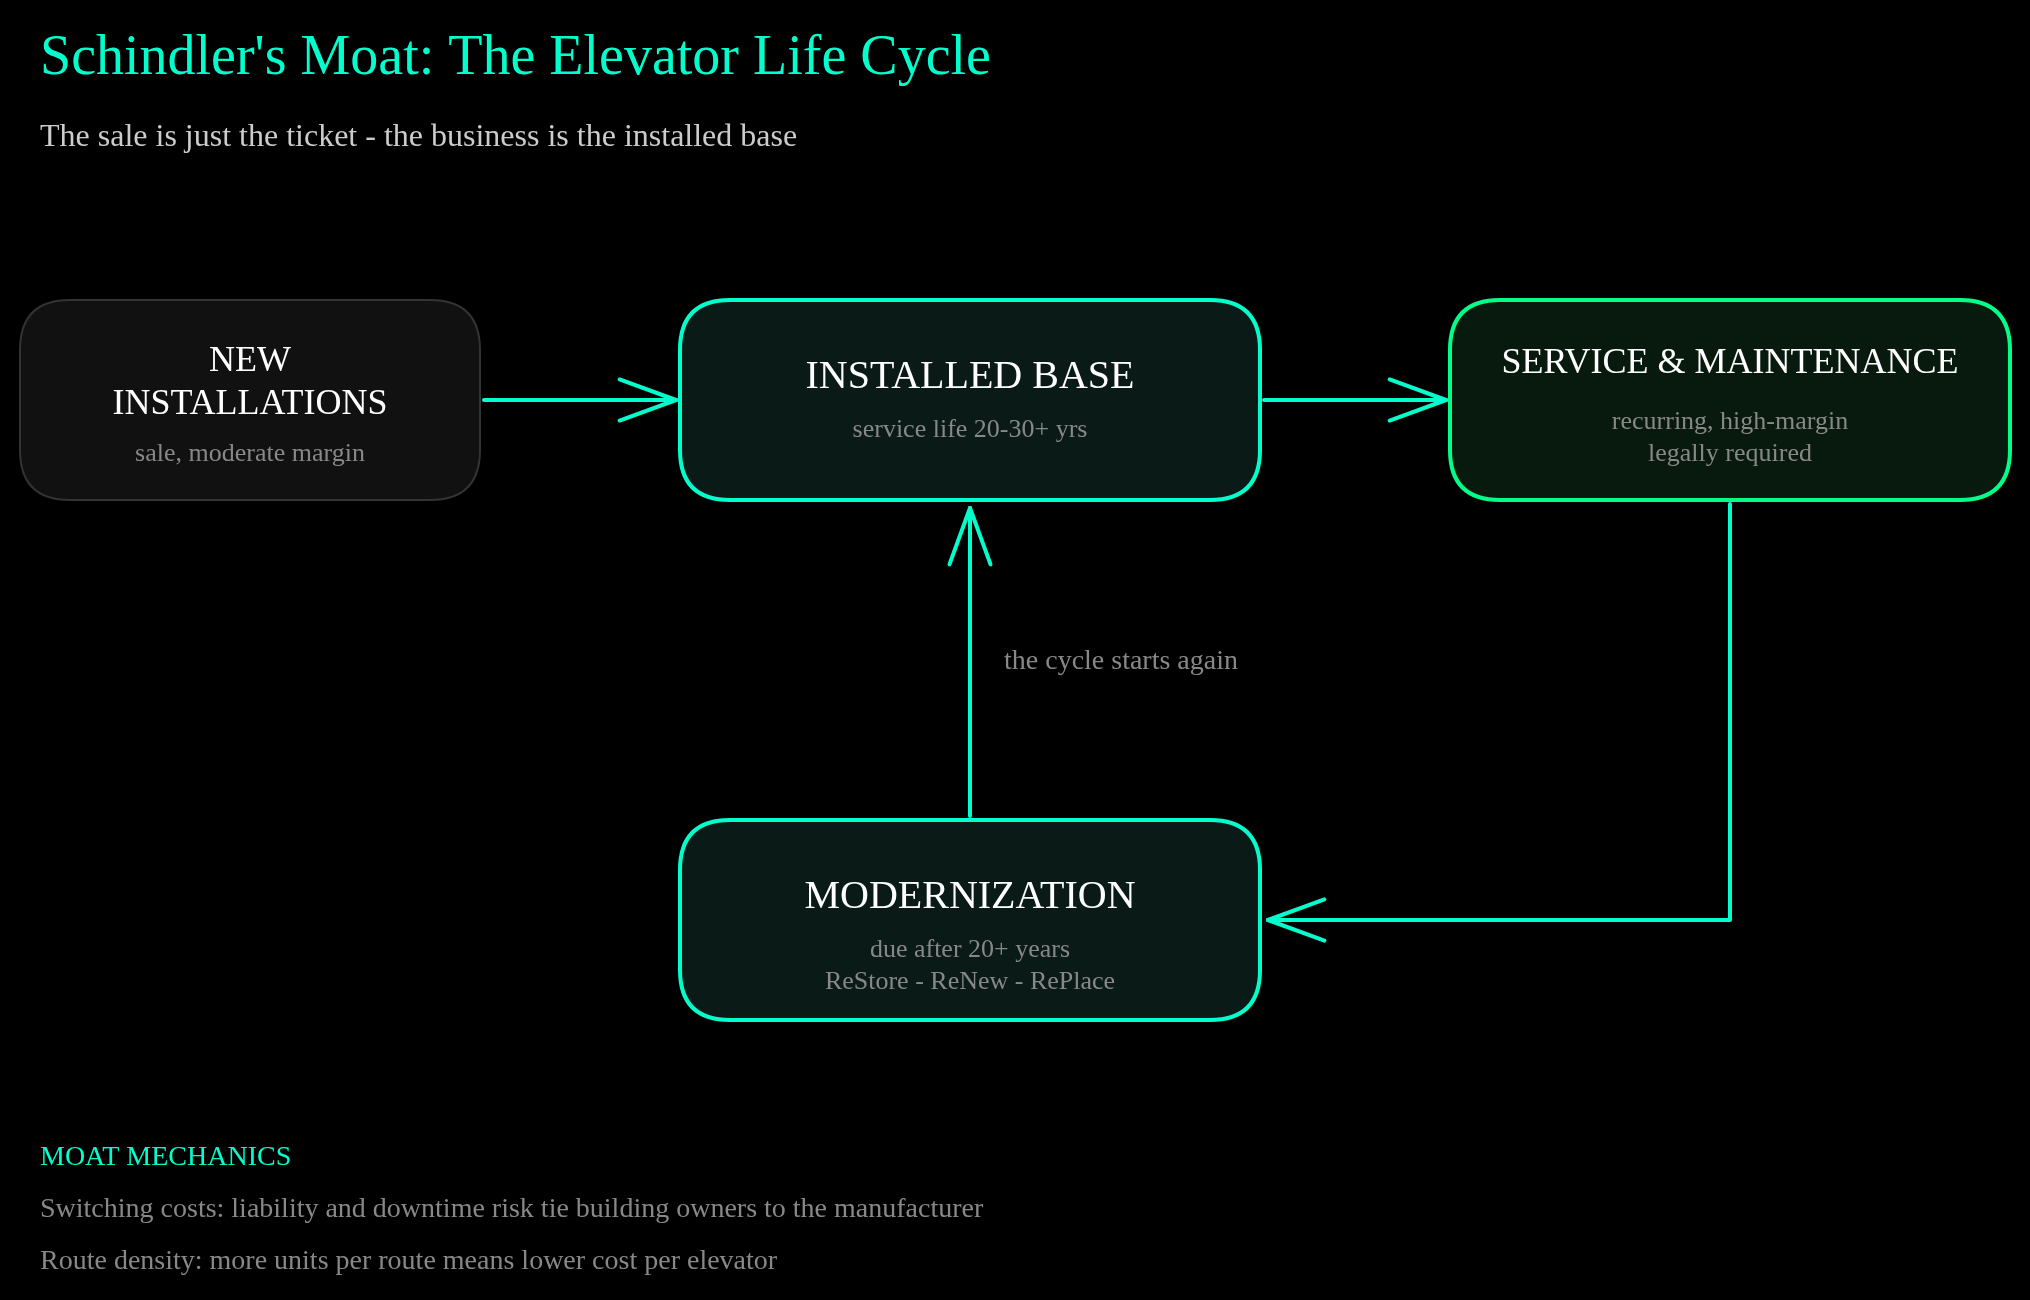
Three business areas, one loop. New installations are the ticket into the building. The installed base then generates recurring, high-margin, legally mandated service revenue for decades. After 20+ years the unit needs modernization, and the cycle starts again.
Four layers protect this loop:
- Switching costs: a stopped elevator in a hospital or office tower is a liability problem. Nobody switches maintenance partners to save a few francs.
- Route density: the more units a technician services per route, the lower the cost per elevator. Small competitors cannot match this.
- Technology: cloud-connected units, remote diagnostics, predictive maintenance. Faults get fixed before the elevator fails.
- Regulation: safety-critical infrastructure does not go to the cheapest bidder.
61% of Schindler's 67,381 employees work in installation and maintenance. This is a service company that also builds elevators, not the other way around.
────────────────
The numbers: flat revenue, surging profit
Revenue 2021 to 2025 looks flat in Swiss francs, from CHF 11.2bn to CHF 10.9bn. That is almost entirely the strong franc, which cost CHF 431m of revenue in 2025 alone. In local currencies the business grew.
The real story is the margin. After the 2022 slump (supply chains, inflation, China lockdowns), management lifted the EBIT margin from 8.0% to 12.6%. EPS went from CHF 5.67 to a record 9.48. The first half of 2026 continued the trend: 13.2% EBIT margin, guidance confirmed.
The dividend followed: CHF 6.80 per unit for 2025, growing at roughly 11% per year over the past five years. Funded from profits, not from substance.
────────────────
SCHN vs. SCHP: co-earner, not co-decider
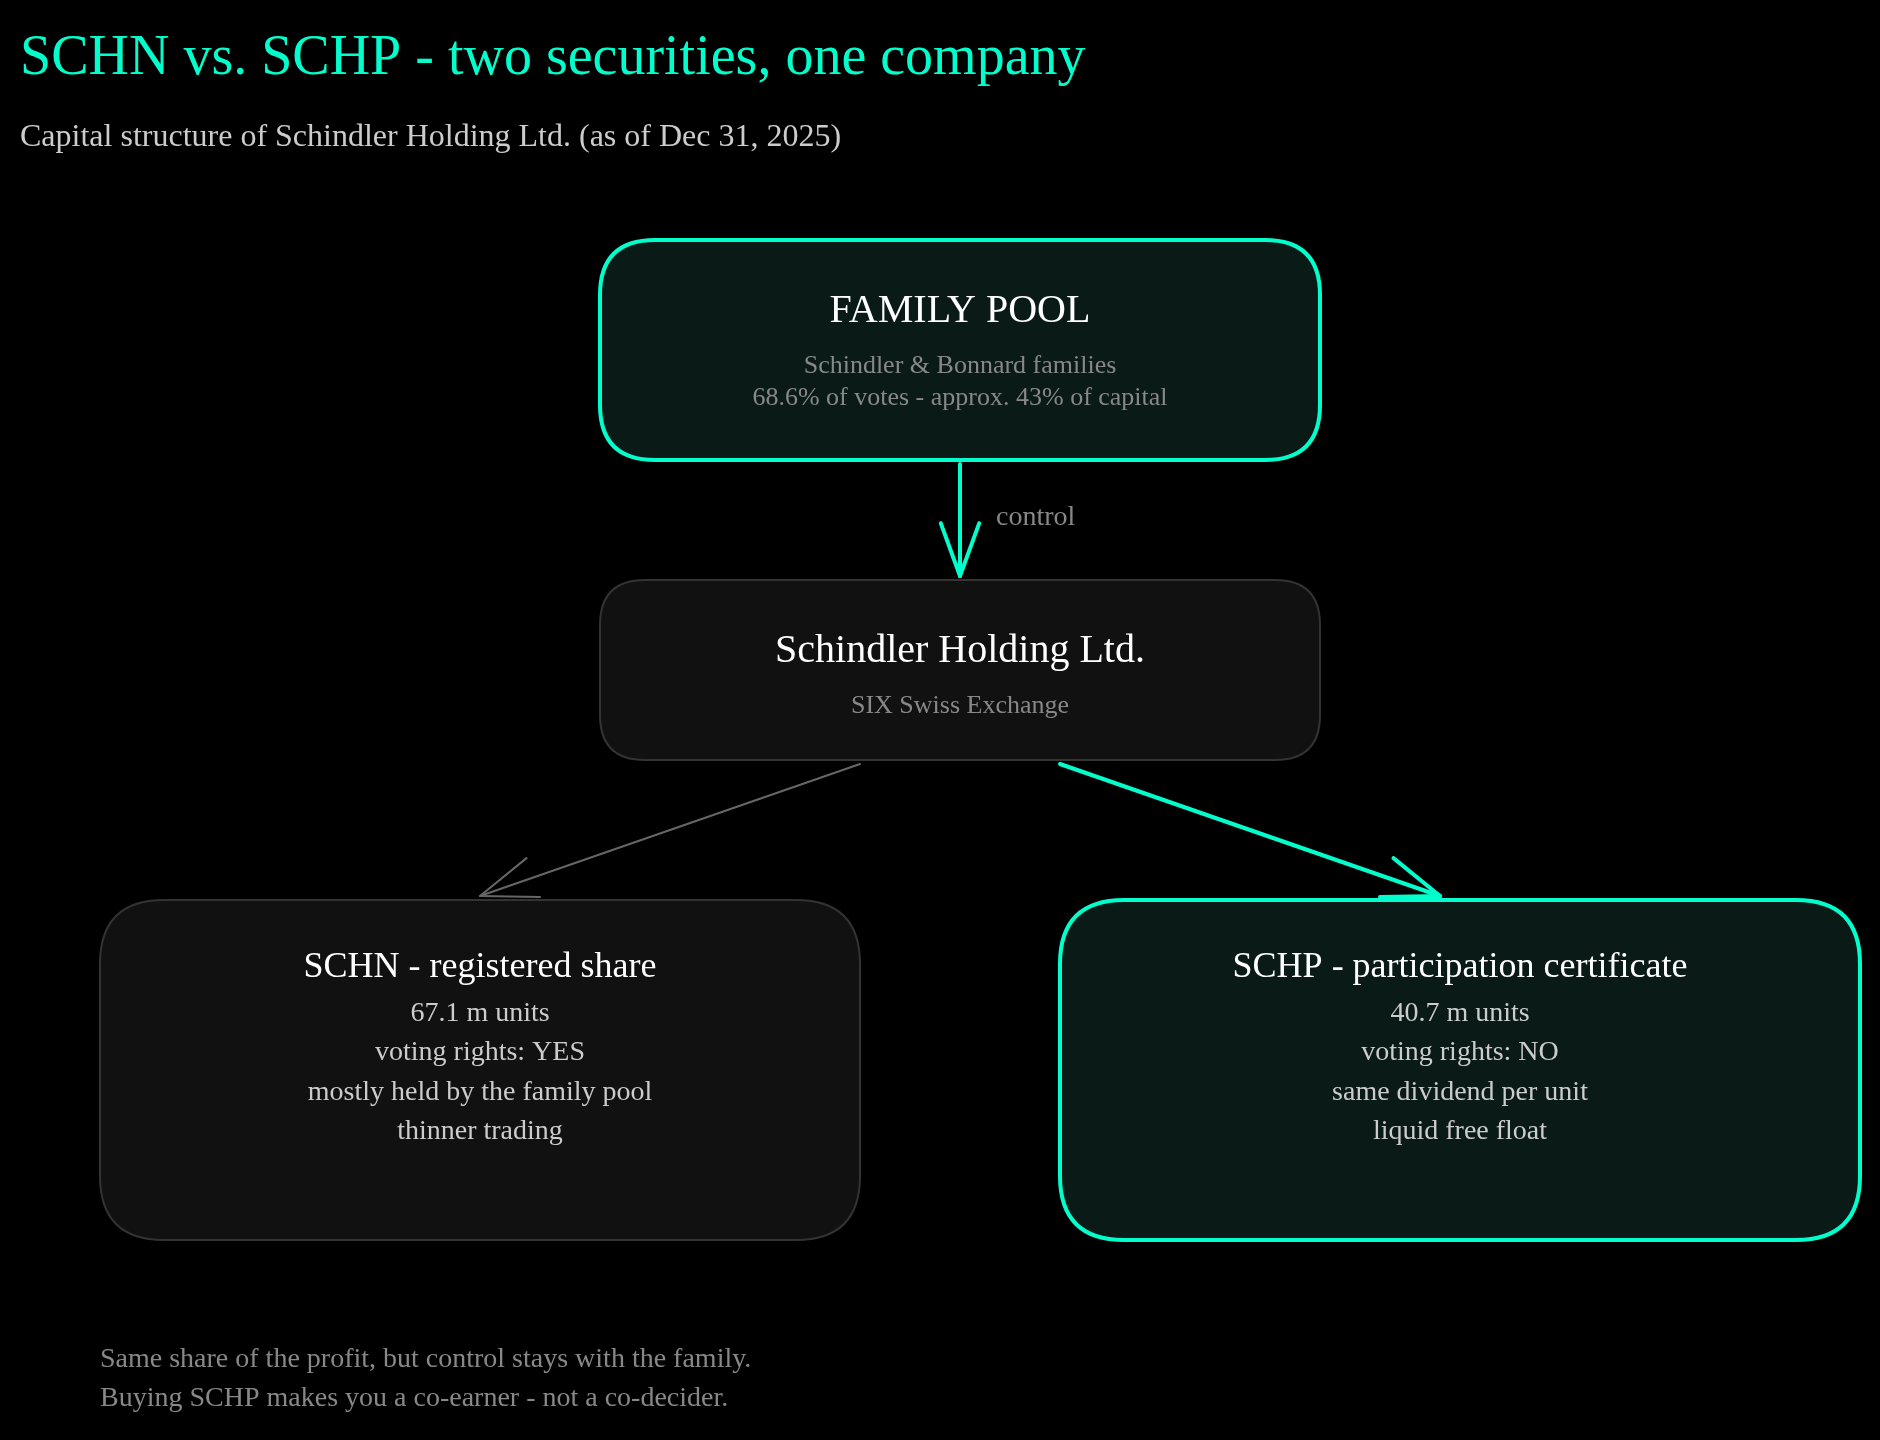
A Swiss peculiarity you need to understand before buying anything here. There are two securities: the registered share SCHN carries voting rights and sits mostly in the pool of the founding Schindler and Bonnard families, which controls 68.6% of the votes with roughly 43% of the capital. The participation certificate SCHP has no vote at all, but exactly the same dividend per unit, and it is the more liquid paper.
Buying SCHP makes you a co-earner, not a co-decider. The family decides, you collect. The past decades suggest that trade has worked out fine for certificate holders.
────────────────
The elephant in the elevator shaft: KONE + TKE
In April 2026, KONE announced it will swallow TK Elevator for an enterprise value of EUR 29.4bn. The combined group would be the largest elevator company in the world: roughly EUR 20.5bn of revenue and 3.2 million maintenance units.
Schindler's CEO Paolo Compagna is playing both sides: announcing antitrust scrutiny while openly planning to poach dissatisfied customers, recruit technicians and buy divested assets during the rivals' multi-year integration. Consolidation is a threat on paper and an opportunity in practice.
────────────────
Valuation: quality without a discount
Trailing P/E 27.6 on record profits. P/B around 6. PEG 2.6. Since the margin recovery, the P/E has oscillated roughly between 22 and 32, and today's price sits in the middle of that band.
There is no margin of safety in this valuation, only in the quality of the business. Whoever buys gets a high-margin service subscription with a growing dividend, and accepts that returns must come from profit growth, not from a re-rating. A watchlist stock: interesting whenever the market grants it a P/E near 22 again.
Not financial advice, just a reading of the numbers.
The full analysis with charts, quality check and all sources:
https://alien-investor.org/en/schindler-schp-aktienanalyse.html
────────────────
📖 GrapheneOS: Android in the Age of Surveillance — Setup, Apps & Digital Sovereignty. The complete handbook for your Google-free Android. DRM-free. 👉 https://alien-investor.org/buecher.html · also on Amazon KDP
🔧 Alien Phone Service — GrapheneOS professionally installed and configured, delivered to your door. No flashing required. Bitcoin or Fiat. 👉 https://alien-investor.org/en/grapheneos-flash-service.html
🛡️ Privacy & Mail — Email, VPN, Cloud without Big Tech. I use Proton. 👉 https://alien-investor.org/proton
₿ Bitcoin in self-custody — Hardware wallet instead of exchange account. Code ALIENINVESTOR = 5% discount on the BitBox. 👉 https://alien-investor.org/bitbox
₿ Bitcoin DCA (Europe) — Bitcoin-only, no shitcoin noise. Code ALIENINVESTOR = permanent −0.2% fee reduction. 👉 https://alien-investor.org/21bitcoin
Disclaimer: Some links are affiliate links. Using them supports this channel at no extra cost to you.
────────────────
Money, power, Bitcoin — and OPSEC. I write about financial sovereignty, privacy, and cybersecurity in a world built on control. More at alien-investor.org 👽
Comments0
No comments yet. Start the conversation.